

Businesses often own valuable assets that are not being fully utilized. These assets may include commercial properties, industrial equipment, machinery, land, inventory, intellectual property, and future revenue streams. Although they can represent significant economic value, converting that value into accessible capital is not always easy. Traditional financing methods may involve lengthy approval processes, strict collateral requirements, ownership dilution, or complex legal procedures.
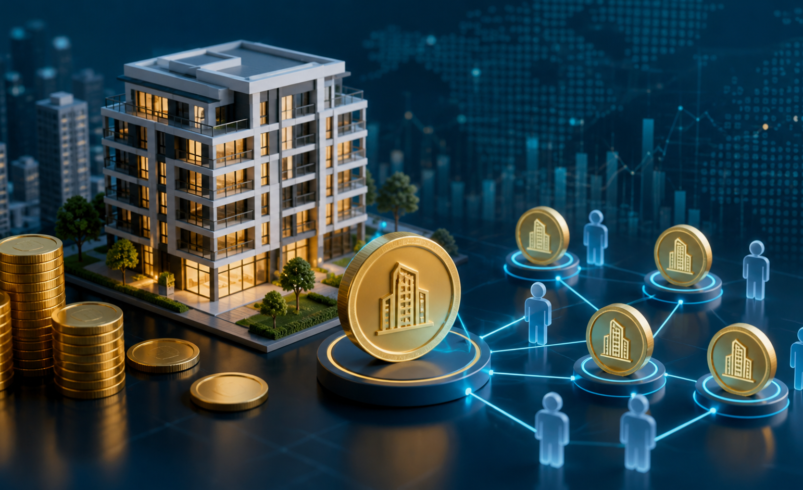
Asset tokenization offers a new approach to connecting underutilized asset value with business financing opportunities. By representing eligible asset ownership interests, financial claims, or economic rights through blockchain-based digital tokens, businesses can explore alternative ways to structure funding and investment opportunities.
Rather than selling an entire asset or relying exclusively on conventional loans, a company may be able to structure a token-based offering around a clearly defined portion of its asset value. Depending on the legal structure, this approach can help businesses attract eligible investors, organize asset-related information, and establish more flexible capital-raising models.
What Is Asset Tokenization?
Asset tokenization is the process of representing ownership interests, financial claims, or other defined rights connected to an asset through digital tokens on a blockchain.
The underlying asset may be physical, such as real estate, gold, or industrial machinery, or financial and intangible, such as bonds, receivables, contractual income, and intellectual property rights.
Each token represents the rights established by the relevant legal and commercial arrangements. Depending on the structure, token holders may receive an ownership interest, a contractual payment entitlement, a share of eligible income, or another defined benefit.
For example, a manufacturing company may own specialized equipment that is valuable but does not generate enough immediate cash to support its expansion plans. Instead of selling the equipment, the company could explore a asset tokenization model linked to a legally defined financial interest in the asset or its associated cash flows.
If structured appropriately, investors could contribute capital in exchange for those defined rights. The business could then use the proceeds for expansion, operational improvements, or other permitted purposes.
The key principle is that tokenization can create a structured connection between existing asset value and potential financing opportunities without necessarily requiring the complete sale of the underlying asset.
Why Do Businesses Have Dormant Asset Value?
Dormant asset value refers to economic value tied up in assets that are not being used to their full potential or are difficult to convert into immediate working capital. An asset does not need to be physically idle to fall into this category. Even productive assets can have value that remains inaccessible for certain financing purposes.
Several situations can create this challenge.
1. Underutilized Physical Assets
Businesses may own warehouses, commercial buildings, production machinery, vehicles, or land that is not generating its maximum potential economic return. Selling these assets may interrupt operations or require the business to give up future benefits.
Tokenization can provide a way to explore funding structures linked to eligible interests in these assets while allowing the business to retain operational use, where the legal arrangement permits it.
2. Capital Locked in Long-Term Investments
Some businesses invest heavily in infrastructure, equipment, property, and specialized facilities. These investments may support future growth but cannot always be converted into cash quickly without selling the assets or taking on additional debt.
A properly structured tokenization model may enable a business to raise capital against defined asset-related rights instead of relying solely on asset liquidation.
3. Delayed Payments and Future Receivables
Companies frequently wait for customers to settle invoices or for contractual payments to become due. Although these receivables represent expected income, they may not immediately support day-to-day expenses.
Eligible receivables can potentially be incorporated into tokenization-based financing structures, subject to verification, transfer restrictions, debtor arrangements, and applicable law.
4. Valuable Rights That Are Difficult to Finance
Businesses may hold licensing rights, royalty agreements, intellectual property interests, or contractual revenue entitlements. These rights can generate economic value without being easy to use as conventional collateral.
Tokenization may help represent clearly defined financial interests associated with such rights, making it possible to explore new funding arrangements.
The objective is not to tokenize every asset a business owns. It is to identify assets or rights with a credible economic basis and determine whether a suitable tokenization structure can create practical financing opportunities.
How Asset Tokenization Turns Dormant Value Into Business Capital
Asset tokenization connects an existing asset or legally defined financial interest with a digital representation that can be incorporated into a financing or investment arrangement.
The process generally involves several stages.
Step 1: Identify and evaluate suitable assets
The business identifies assets or rights that may support a funding opportunity. Their ownership, market value, income potential, existing liabilities, and restrictions must be evaluated before proceeding.
Step 2: Establish the legal structure
Legal and financial professionals determine what investors will receive. This may involve an ownership interest, a debt instrument, a contractual payment claim, or rights held through a special-purpose vehicle (SPV), depending on the transaction.
Step 3: Define the token structure
The issuer determines token supply, investor eligibility, pricing, distribution rules, transfer restrictions, and any applicable income or repayment terms.
Step 4: Develop and test the platform
Smart contracts and supporting platform components can automate eligible processes, such as token issuance, transfer restrictions, investor records, and payment calculations. Independent testing and security reviews are important before launch.
Step 5: Raise capital from eligible investors
Tokens can be offered through an appropriate distribution model to eligible investors. The funds raised may support approved business activities, subject to the offering terms and legal requirements.
Step 6: Manage the asset and investor obligations
Following issuance, the business or its appointed service providers maintain asset-related records, report relevant performance, and administer distributions, repayments, or other obligations under the agreed terms.
A successful implementation depends on more than blockchain technology. The financial structure, investor rights, and real-world asset arrangements must work together throughout the asset’s lifecycle.
Which Assets Can Businesses Tokenize to Unlock Capital?
Different asset categories offer different financing possibilities. The most suitable approach depends on the asset’s value, cash-flow profile, legal ownership, and ability to support enforceable investor rights.
1. Real Estate and Commercial Property
Commercial buildings, warehouses, rental properties, and other eligible real estate assets can hold substantial value while requiring significant capital for maintenance, expansion, or new projects.
Through real estate tokenization, a business may structure an offering linked to ownership interests or defined economic rights associated with a property. Investors may receive rights to eligible rental income, distributions, or proceeds from a future sale, depending on the legal structure.
For example, a company holding a leased commercial building could evaluate whether a property-owning SPV and a compliant token offering could help finance a new development without selling the entire building.
2. Industrial Equipment and Machinery
Manufacturing businesses often invest in specialized equipment, production lines, and heavy machinery. These assets support revenue generation but can also tie up significant amounts of capital.
Tokenization may allow a business to explore financing linked to eligible equipment ownership interests, secured obligations, or contractual cash flows. The structure must account for depreciation, maintenance costs, insurance, existing liens, and the consequences of equipment failure.
This approach may be particularly relevant when a company wants to expand production capacity while preserving access to essential machinery.
3. Trade Receivables and Invoices
Outstanding invoices can represent a meaningful source of potential working capital. Rather than waiting for payment deadlines, businesses may explore financing against eligible receivables.
A tokenization structure could digitally represent defined payment claims or interests in a pool of verified invoices. Investor returns would depend on the contractual terms, collections, debtor performance, and applicable fees.
Careful verification is essential to avoid duplicate financing, disputed claims, and uncertainty over who has the legal right to collect the underlying payments.
4. Inventory and Commodities
Businesses holding eligible inventory, raw materials, or commodities may be able to explore asset-backed financing models. Tokenization can support the digital representation of defined interests in properly documented and controlled assets.
For instance, a commodity business could investigate a structure linked to verified, stored inventory. The arrangement would need reliable custody, asset identification, insurance, valuation, and procedures for handling shortages or changes in market prices.
Tokenization does not eliminate storage expenses or price volatility, but it may provide an alternative framework for organizing investment and financing arrangements.
5. Intellectual Property and Royalty Rights
Patents, licensing agreements, copyrights, and other eligible intellectual property rights can generate royalties or contractual income.
A business may explore tokenization of defined royalty entitlements or other legally transferable economic rights. This could create a financing opportunity based on existing or projected revenue, depending on the quality of the underlying agreements.
The structure must distinguish between rights to receive payments and ownership of the intellectual property itself. Token holders should not be assumed to acquire control over the underlying IP unless the governing documents explicitly grant it.
6. Energy and Infrastructure Assets
Renewable energy facilities, utility infrastructure, telecommunications assets, and other long-term projects can require substantial upfront investment while generating revenue over extended periods.
Tokenization may provide a framework for structuring investment interests or contractual cash-flow entitlements associated with eligible projects. This can help businesses explore funding from multiple eligible investors, subject to project economics, permits, contractual arrangements, and regulatory requirements.
Infrastructure projects require particularly careful planning because revenues may depend on operating performance, energy prices, offtake contracts, and long-term maintenance obligations.
Business Benefits of Asset Tokenization
Asset tokenization can offer several potential advantages when it is supported by a commercially viable asset and a legally sound structure.
Improved Access to Capital
Businesses may gain an additional financing channel beyond traditional bank loans, private investment, or asset sales. A suitable offering can connect eligible assets with investors whose investment requirements align with the opportunity.
This does not guarantee that capital will be raised. Investor demand, transaction costs, offering restrictions, and the quality of the underlying asset remain important factors.
More Flexible Financing Structures
Tokenization can support different approaches to financing. A business may explore debt-based arrangements, equity interests, revenue-linked rights, or other permitted structures.
This flexibility can help companies evaluate financing options that reflect the asset’s characteristics and their own capital requirements. Each arrangement must clearly establish repayment obligations, distributions, risk allocation, and investor rights.
Potential for Fractional Investment
Instead of requiring one investor to finance an entire asset or transaction, a token offering may divide eligible investment interests into smaller units.
This can broaden access to an offering among eligible investors, depending on applicable minimum investment requirements and securities rules. Fractional representation does not automatically make an asset affordable, liquid, or suitable for every investor.
Greater Recordkeeping Transparency
Blockchain-based records can provide a shared, time-stamped history of token issuance and eligible transfers. Smart contracts can also support the consistent application of certain transaction rules.
However, blockchain records alone do not prove that an underlying asset exists, establish legal ownership, or guarantee that off-chain records are accurate. Independent verification and appropriate governance remain necessary.
Retaining Strategic Control Over Assets
In certain structures, a company may raise capital against defined financial rights while retaining possession or operational use of an asset. This may be useful for businesses that need funding but cannot afford to interrupt production, sell critical equipment, or dispose of a strategically important property.
Whether control can be retained depends on the legal structure, collateral arrangements, investor rights, and any applicable enforcement provisions.
Potential for Broader Investor Participation
Digital distribution infrastructure may help issuers reach eligible investors across multiple markets, where legally permitted. This can create opportunities to explore cross-border capital formation.
However, international distribution introduces additional requirements involving investor eligibility, securities laws, taxation, foreign exchange, marketing restrictions, and transfer controls.
Practical Use Cases: Turning Idle Assets Into Funding Opportunities
Understanding how asset tokenization works in real business situations helps explain its potential value.
Case 1: A Property Company Financing Expansion
Consider a property company that owns a commercial building generating rental income. The company wants to develop another property but does not want to sell its existing building.
It could evaluate a tokenization structure linked to a legally defined interest in the existing property’s economics. Eligible investors might contribute capital in exchange for the rights specified in the offering documents.
The company could use the proceeds to support its new development, while the existing property’s income and expenses continue to be managed according to the agreed structure.
The potential benefit is an alternative funding route that does not necessarily require the outright sale of the original property.
Case 2: A Manufacturer Unlocking Equipment Value
A manufacturing company owns expensive machinery that is essential to its production operations. It needs additional capital to purchase equipment and enter a new market.
Instead of selling its existing machinery, the company could assess a financing arrangement supported by eligible equipment-related interests or contractual obligations.
If the transaction is viable and properly structured, investors could supply capital under agreed terms. The company would need to account for the machinery’s valuation, existing security interests, operating risks, and the rights available to investors.
Case 3: A Business Financing Outstanding Invoices
A growing business has completed several projects but must wait 60 to 90 days for customer payments. Meanwhile, it needs cash to pay suppliers, employees, and operating expenses.
The business could explore a tokenization-based financing structure involving verified receivables. Investors would fund eligible payment claims under documented terms, and collections would be handled according to the agreed arrangement.
This approach could help address a timing gap between delivering services and receiving payment, although debtor defaults, disputes, and collection delays would still present risks.
These examples illustrate potential applications rather than guaranteed outcomes. Businesses should compare tokenization with conventional financing and other alternatives before choosing a structure.
Asset Tokenization vs. Traditional Asset Financing
Asset tokenization does not replace every traditional financing method. Its value depends on whether digital infrastructure and a particular legal structure offer meaningful advantages for a specific transaction.
| Factor | Traditional asset financing | Tokenization-based financing |
|---|---|---|
| Funding structure | Loans, secured credit, asset sales, or private investment | Digitally represented ownership interests, claims, or financial rights |
| Investor participation | Often depends on the lender or transaction structure | May support participation by multiple eligible investors |
| Recordkeeping | Conventional legal, financial, and administrative systems | Blockchain records alongside legal and off-chain records |
| Payment administration | Managed through agreed banking and servicing processes | May combine conventional payment systems with smart-contract automation |
| Transferability | Governed by loan terms, contracts, and applicable law | Governed by token rules, legal rights, and applicable transfer restrictions |
| Implementation | Requires credit assessment, documentation, and financing arrangements | Also requires token infrastructure, cybersecurity, legal structuring, and ongoing platform management |
The important distinction is that tokenization changes how certain financial interests may be represented, administered, and distributed. It does not automatically improve the underlying asset’s quality or eliminate the need for legal enforcement.
Challenges Businesses Must Consider Before Tokenizing Assets
Despite its potential, asset tokenization involves financial, technical, operational, and regulatory challenges. Addressing these issues early can help businesses avoid expensive mistakes.
1. Legal Ownership and Enforceable Rights
The issuer must establish who legally owns the asset and what rights can be offered to investors. Existing mortgages, liens, leases, contractual restrictions, and third-party claims may affect the transaction.
Token holders must understand whether they receive direct ownership, an interest through an SPV, a debt claim, or a contractual entitlement. A digital token should not be treated as proof of legal ownership unless the applicable legal framework supports that conclusion.
2. Asset Valuation and Verification
An inaccurate valuation can create unrealistic funding expectations or expose investors to unnecessary risk. Businesses need credible valuation methods, appropriate supporting documents, and verification of the underlying asset or claim.
For income-generating assets, projected revenue should be assessed alongside operating expenses, maintenance, taxes, and potential periods of reduced income.
3. Regulatory Compliance
Token offerings may be subject to securities laws, financial promotion rules, anti-money laundering requirements, know-your-customer procedures, data protection obligations, and other jurisdiction-specific regulations.
The applicable requirements depend on the asset, the rights offered, the issuer, the investor base, and the countries involved. Businesses should obtain qualified legal advice before marketing or distributing tokens.
4. Technology and Cybersecurity
Smart contracts and token platforms must be designed to enforce the intended rules reliably. Coding errors, compromised administrative keys, unauthorized access, and integration failures can create significant risks.
Security testing, independent audits, access controls, incident-response plans, and clearly defined upgrade procedures are important elements of a responsible implementation.
5. Investor Demand and Liquidity
Creating tokens does not guarantee investor demand or an active secondary market. Some tokens may be subject to strict transfer restrictions, and buyers may be difficult to find when an investor wants to exit.
Businesses should evaluate likely investor interest, offering costs, holding periods, exit arrangements, and realistic liquidity expectations before proceeding.
6. Ongoing Asset Management
Tokenization does not remove the responsibilities associated with managing the underlying asset. Property still requires maintenance, equipment needs servicing, and receivables require collection.
Issuers must also maintain accurate records, provide required disclosures, administer payments, and respond to changes in the asset’s financial or legal position.
How to Build an Effective Asset Tokenization Strategy
Businesses should approach tokenization as a financing and operational strategy rather than a technology experiment.
The following framework can help establish a practical starting point.
Identify the business objective
Define whether the goal is to finance expansion, improve working capital, refinance existing obligations, monetize eligible asset rights, or attract investment for a new project.
Select assets with a clear economic purpose
Prioritize assets with verifiable ownership, credible valuation, understandable financial characteristics, and a commercially reasonable funding case.
Choose an appropriate financial model
Determine the rights being offered, expected funding requirements, investor eligibility, repayment or distribution mechanisms, and potential exit arrangements.
Develop the legal and technology framework
Establish the offering documentation, compliance procedures, smart-contract requirements, custody arrangements, reporting systems, and security controls.
Assess commercial viability before launch
Estimate development and administration costs, evaluate investor demand, compare alternative financing options, and establish a plan for ongoing asset management.
A phased implementation can help businesses validate their assumptions before committing substantial resources. Starting with one well-defined asset or asset class may be more practical than launching a platform intended to support every possible asset category from the beginning.
The Role of an Asset Tokenization Development Company
Building an asset tokenization solution involves more than deploying smart contracts. Businesses may need technical expertise to connect their asset records, legal structures, investor onboarding, token issuance, payment processes, and reporting systems.
An asset tokenization development company can support this process by helping design and build the technology infrastructure required for the intended business model.
Depending on the project’s scope, development services may include:
-
Token architecture: Designing token functionality around the intended ownership interests, financial claims, or contractual rights.
-
Smart contract development: Implementing issuance rules, transfer restrictions, payment logic, and other permitted automated processes.
-
Platform development: Building investor interfaces, administrative dashboards, asset information pages, and transaction management features.
-
Compliance integrations: Supporting identity verification, investor eligibility checks, and relevant compliance workflows through suitable integrations.
-
Payment and reporting systems: Connecting payment administration, transaction histories, and asset-performance reporting.
-
Security and maintenance: Supporting testing, security reviews, monitoring, upgrades, and ongoing technical improvements.
A company such as Inoru, which provides tokenization development services, can be considered when a business is evaluating the technology needed to build an asset tokenization platform. The appropriate development partner should be selected based on its technical capabilities, relevant experience, security practices, and ability to work alongside legal and financial professionals.
The final solution should reflect the actual rights and obligations of the transaction rather than relying on a generic token model.
The Future of Asset Tokenization in Business Financing
Asset tokenization is creating new possibilities for businesses to examine how they finance and manage valuable assets. As blockchain infrastructure, digital identity systems, compliance tools, and institutional participation develop, tokenization may become an increasingly relevant component of certain capital-raising strategies.
One potential area of growth is the combination of different asset categories within a single investment framework. For example, a business could explore financing structures that connect commercial property with contractual rental income or industrial equipment with defined payment obligations.
Another opportunity lies in improving the administration of asset-backed financial arrangements. Digital records, automated calculations, and controlled transfers may reduce certain administrative burdens when supported by accurate underlying data and appropriate legal processes.
Cross-border financing is another area of interest. Digital infrastructure may help issuers coordinate investor participation across markets, but this will depend on regulatory compatibility, investor protections, payment infrastructure, and enforceable rights in the relevant jurisdictions.
The long-term opportunity is not simply to create more digital tokens. It is to develop reliable ways to connect real economic value with suitable sources of capital.
Businesses that focus on transparent structures, credible assets, and practical financing objectives are better positioned to assess where tokenization may offer meaningful benefits.
Conclusion
Asset tokenization offers businesses an alternative way to approach dormant asset value. By representing eligible ownership interests, financial claims, or economic rights through blockchain-based tokens, companies can explore new financing structures without necessarily selling an entire asset or relying exclusively on conventional borrowing.
From commercial property and industrial machinery to receivables, intellectual property, and infrastructure, different assets may support different tokenization models. The right approach depends on the asset’s economic characteristics, legal status, investor demand, and the business’s funding requirements.
However, tokenization is not a guaranteed source of capital, and it does not automatically create liquidity or eliminate financing risks. Legal clarity, credible valuation, regulatory compliance, technology security, and ongoing asset management remain essential.