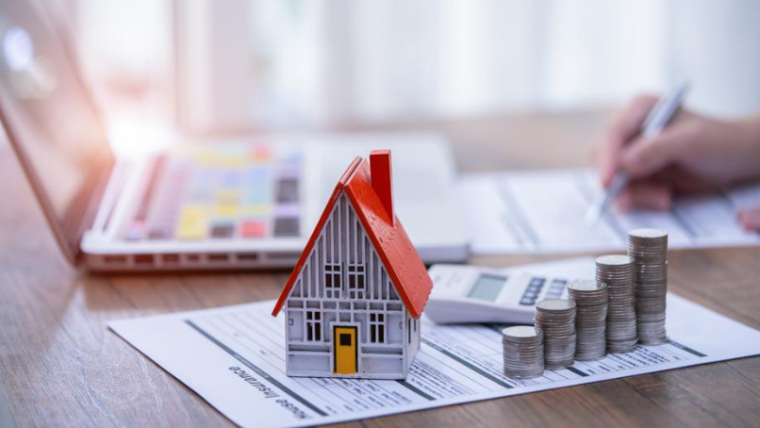


Purchasing a home is a major financial commitment that requires more preparation than simply saving for a down payment. Buyers must understand their borrowing capacity, evaluate the property’s condition, and plan for expenses that continue long after the purchase is complete. Making these decisions carefully can reduce financial uncertainty and help homeowners feel more prepared for the responsibilities ahead.
For buyers exploring a Mortgage lender in Lubbock County, Texas, learning how mortgage applications work and what influences loan affordability can make the financing process easier to navigate. Comparing repayment terms, reviewing lender fees, and understanding local ownership expenses are useful steps before choosing a mortgage.
The most suitable financing arrangement is one that fits the buyer’s financial situation without leaving too little room for everyday needs or unexpected costs. With a realistic budget and a clear understanding of the lending process, prospective homeowners can make better decisions from the initial application through closing and beyond.
Set Realistic Expectations Before Viewing Properties
House hunting can quickly become overwhelming when buyers focus on attractive properties before determining what they can afford. Establishing a practical price range first helps narrow the search and reduces the temptation to stretch beyond a comfortable budget.
Start by reviewing income, existing debts, recurring expenses, and savings goals. Then estimate the complete monthly cost of owning a home, including principal, interest, property taxes, insurance, utilities, and maintenance.
It is also helpful to distinguish essential features from optional preferences. A smaller property that meets your needs may provide greater financial flexibility than a more expensive home requiring a larger mortgage. A realistic starting point can make the entire buying process more focused and manageable.
Learn How Mortgage Prequalification and Preapproval Differ
Prequalification and preapproval can help buyers understand their potential financing options, but they are not always the same process. Prequalification may provide an initial estimate based on information supplied by the borrower, while preapproval often involves a more detailed review of financial information.
The exact procedures vary among lenders, so buyers should ask what has actually been verified and which conditions remain outstanding. Neither process necessarily guarantees final mortgage approval.
A preapproval may help buyers establish a working budget before making an offer. However, the lender will generally still need to complete underwriting, evaluate the property, and confirm that all applicable requirements have been met. Understanding these distinctions helps buyers avoid treating an early estimate as a final lending commitment.
Choose a Loan Structure That Matches Your Plans
Mortgage products differ in their interest-rate arrangements, repayment periods, eligibility requirements, and associated expenses. A fixed-rate mortgage generally provides a consistent interest rate, while an adjustable-rate mortgage may change according to the terms of the agreement.
The appropriate structure depends partly on how long you expect to own the property, your tolerance for payment changes, and the flexibility of your household budget. Someone who values predictable payments may prefer a different arrangement from a buyer who understands and can manage the risks of an adjustable rate.
Ask lenders to explain the potential payments under different scenarios. Looking beyond the introductory rate can help you understand the financial commitment throughout the period you expect to keep the loan.
Review the Full Cost of Buying in Lubbock County
The purchase price alone does not tell the complete financial story. Buyers in Lubbock County should also consider property taxes, homeowners insurance, utilities, commuting costs, and possible maintenance expenses.
Texas property taxes vary according to taxable value, applicable taxing jurisdictions, and any eligible exemptions. Reviewing available property-specific tax information can provide a more useful estimate than relying on a general countywide figure.
Insurance expenses also deserve attention before an offer becomes final. The property’s age, construction, coverage needs, and deductible can influence premiums. Gathering these estimates early helps buyers determine whether a home will remain affordable once all recurring expenses are included.
Understand the Role of Your Credit History
Credit history helps lenders evaluate how applicants have managed previous financial obligations. Payment records, credit utilization, outstanding debts, and other information may influence mortgage eligibility and the terms offered.
Before applying, review your credit reports for errors and address any inaccuracies through the appropriate reporting agencies. Maintaining timely payments and avoiding unnecessary new debt can also help protect your financial position.
If your credit profile needs improvement, ask lenders which requirements apply to the mortgage programs you are considering. Different loan options may have different eligibility standards, so a single credit-related concern does not necessarily determine every available choice. Taking time to understand your position can help you prepare a more complete application.
Budget for Expenses That Arise Before Closing
The period between an accepted offer and closing can involve several expenses. Depending on the transaction, buyers may pay for inspections, appraisals, earnest money, option-related costs under the contract, or other services.
Some amounts may be credited toward the purchase or closing, while others represent separate expenses. The exact treatment depends on the contract, lender requirements, and transaction details.
Ask your real estate and mortgage professionals to explain which payments are required, when they are due, and whether they are refundable or credited under the applicable terms. Keeping a written record of deadlines and amounts helps prevent confusion and ensures that you maintain sufficient funds throughout the purchase.
Compare Lender Fees and Repayment Conditions
Two mortgage offers with similar interest rates can have different total costs. Origination charges, discount points, mortgage insurance, and other expenses may influence which option provides better value.
Request written Loan Estimates from multiple lenders and compare them using similar loan amounts, down payments, and repayment periods. Review the annual percentage rate, estimated monthly payment, closing costs, and cash required to complete the transaction.
Also ask whether the interest rate is locked, how long the lock lasts, and what could cause the quoted terms to change. Understanding these details allows borrowers to evaluate offers based on documented costs rather than relying exclusively on an advertised rate.
Prepare for the Appraisal and Home Inspection
A mortgage appraisal helps the lender evaluate the property’s market value, while a home inspection examines its physical condition. Both can provide important information, but they serve different purposes.
If an appraisal comes in below the agreed purchase price, the lender’s calculation may be affected. Depending on the financing terms and purchase contract, the buyer may need to negotiate, provide additional funds, or explore other permitted options.
An inspection may identify concerns involving the roof, foundation, plumbing, electrical systems, or heating and cooling equipment. Buyers should review significant findings carefully and obtain specialist assessments or repair estimates when appropriate. Understanding the property’s condition before closing can help prevent unexpected expenses shortly after moving in.
Keep Your Finances Organized During Underwriting
Mortgage underwriting involves verifying information and confirming that the loan satisfies the applicable requirements. Lenders may request updated statements, proof of income, employment verification, or explanations of particular transactions.
Major changes during this stage can complicate approval. Taking out another loan, making large purchases on credit, changing employment, or moving substantial sums between accounts may require additional review.
Maintain accurate records and respond promptly when documents are requested. If your circumstances change, communicate with the lender rather than assuming the change will not matter. Staying organized can help the transaction proceed more smoothly, although appraisal issues, title matters, and other factors may still affect the timeline.
Evaluate the Quality of Communication From Your Lender
Clear communication is valuable when dealing with mortgage paperwork, financial disclosures, and closing deadlines. Buyers should understand who to contact with questions and how updates will be provided throughout the process.
When considering Hub City Lending, prospective borrowers can ask about available loan options, application requirements, expected timelines, and the fees associated with their proposed financing. They can also compare written offers from other providers and verify relevant licensing information.
A lender’s explanations should make the financial commitment easier to understand, not more confusing. Before agreeing to a mortgage, review the documents carefully and request clarification about anything that remains uncertain. An informed decision depends on understanding the actual terms of the loan.
Plan for Financial Stability After Moving In
The responsibilities of homeownership continue after the keys are handed over. Routine maintenance, repairs, insurance renewals, property tax changes, and other household expenses can affect affordability over time.
Create a maintenance reserve and account for likely repairs involving major systems and appliances. Even a property that appears well maintained can develop unexpected problems, so keeping emergency savings separate from everyday spending is useful.
Review your household budget periodically as income, expenses, and property needs change. If refinancing or making additional principal payments becomes an option later, compare the potential benefits with fees and other financial priorities before proceeding.
Conclusion
Careful mortgage planning can help homebuyers avoid preventable financial surprises and approach property ownership with realistic expectations. Establishing a sensible budget, understanding credit requirements, comparing written loan estimates, and investigating property-related expenses all contribute to a more informed purchase.
For buyers researching financing in Lubbock County, Hub City Lending is one provider to consider alongside other mortgage options. The final decision should be based on verified loan terms, transparent costs, and the borrower’s ability to manage payments over time. With thorough preparation, purchasing a home can become a more structured and financially sustainable step toward long-term stability.